
Do You Need a Pre Purchase Valuation for an Off-the-Plan Property?
You’ve found the display suite, picked your finishes, and signed a contract to buy an apartment or townhouse that doesn’t exist yet. Eighteen months to three years from now, once the building’s finally registered, your lender will send its own valuer through to work out what the finished product is actually worth — and there’s no guarantee that number will match what you agreed to pay.
That gap between your contract price and the bank’s final valuation is one of the biggest financial risks in buying off the plan, and a property value check before signing a contract can provide an independent view of whether the purchase price is supported by current market evidence before you’re locked into a contract you can’t easily walk away from.
This article walks through how off-the-plan valuations actually work, why they’re trickier than valuing an established home, what happens if the numbers don’t line up at settlement, and where an independent pre purchase valuation fits into protecting yourself — plus the contract terms, state-based rules and tax settings every off-the-plan buyer in Australia should have on their radar in 2026.
Summary
Off-the-plan property is different from buying something you can walk through today: you’re agreeing to a price now for a home that might not be finished for one to three years. Two different valuations matter here. The first is a pre purchase valuation — an independent check you can commission before you exchange contracts, to see whether the price you’re agreeing to pay is realistic. The second is the valuation your lender orders closer to settlement, once the building actually exists, to decide how much they’ll lend against it.
The risk is that these two numbers don’t match. Valuers assessing off-the-plan property have to work from plans, finishes schedules and comparable sales in a market that can move significantly between exchange and settlement, and lenders are often cautious about relying on other sales within the same new development as comparable evidence. If the completion valuation comes in below your contract price, your loan is based on the lower figure, and you’re left funding the difference yourself, on top of your deposit.
An independent pre purchase valuation before you sign won’t guarantee the bank’s later number will match, but it gives you an evidence-based read on whether the contract price reflects genuine market value, rather than a developer’s margin, marketing spend and sales incentives baked into the number. It’s also worth understanding what protections already exist in your contract — sunset clauses, cooling-off provisions, deposit trust arrangements — and how stamp duty concessions, grants and the 2026 federal tax changes to negative gearing and capital gains tax treat new builds differently to established homes, since these all affect whether the deal in front of you still makes sense.
The practical takeaway: the bigger your loan, the thinner your buffer, and the less established the developer, the more a pre purchase valuation earns its cost before you exchange.
Why a Pre Purchase Valuation Matters More for Off-the-Plan Property
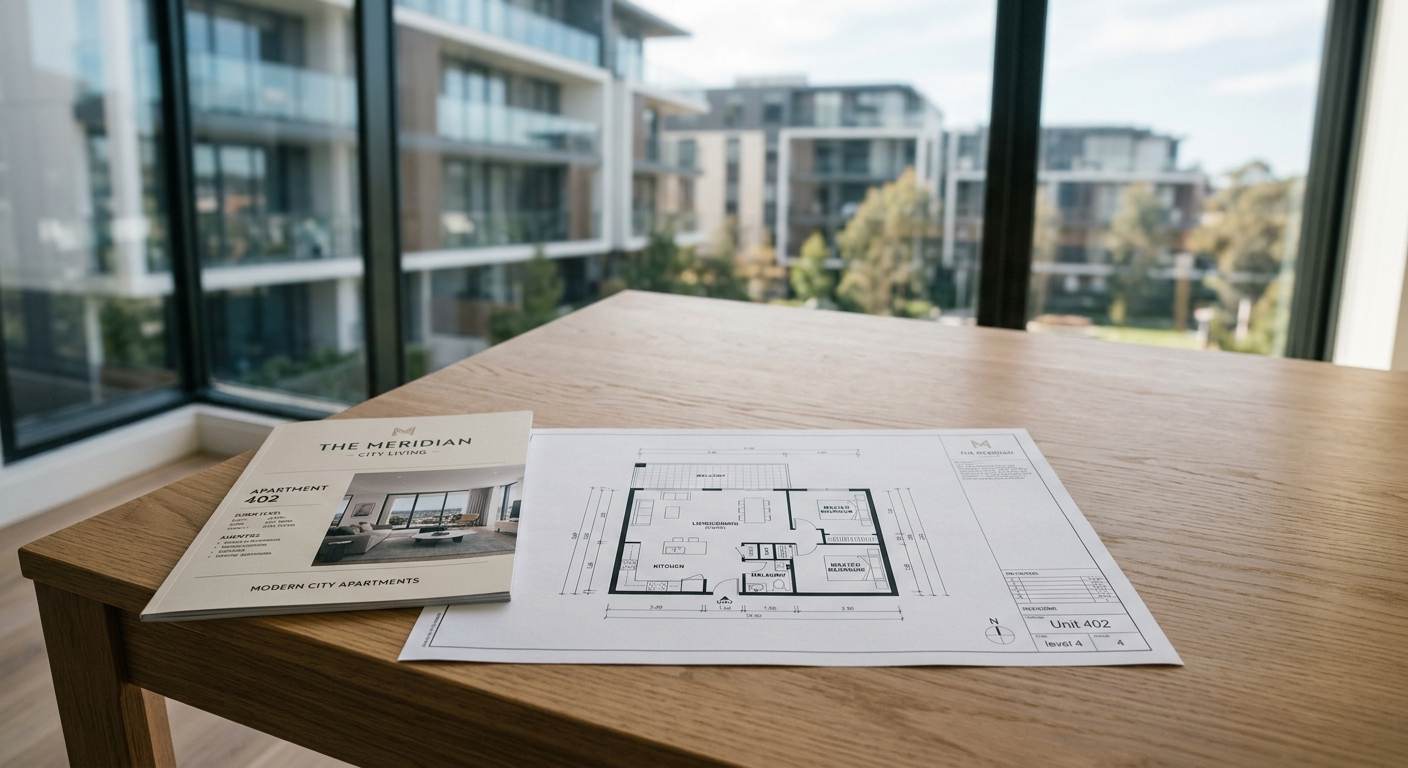
When you buy an established house or unit, you (or your bank) can send a valuer through the front door in settlement week. They walk every room, check the condition, and compare it to recent sales down the street. With an off-the-plan purchase, none of that exists yet — there’s a hole in the ground, or a half-finished frame, and a contract based on architectural plans, an artist’s impression and a finishes schedule.
A pre purchase valuation is an independent assessment of what a property is realistically worth, prepared by a qualified valuer who has no financial interest in the sale going ahead — unlike a real estate agent’s appraisal or a developer’s own sales figures. For an off-the-plan property, that valuer is effectively pricing a promise: they’re working from the plans and specifications to estimate what a similar, finished dwelling would be worth in today’s market.
This is a genuinely different exercise to a bank’s mortgage valuation, which happens later — usually shortly before settlement, once the building exists or is close to it — and exists to protect the lender’s security, not to tell you whether you’re paying a fair price. A pre purchase valuation, ordered independently before you exchange contracts, is squarely there for you: to check whether the number on your contract reflects the market, or whether it’s inflated by developer margin, marketing costs, display suite finishes and sales incentives that don’t necessarily translate into resale or bank valuation value.
How Valuers Actually Assess a Property That Isn’t Built Yet
What They’re Working From
For a property still on the drawing board, a valuer generally does one of two things, or both. If construction hasn’t started, they might value the underlying land on its own. Once there’s enough detail — floor plans, a finishes schedule, a display suite, sometimes a part-built structure — they’ll typically produce what’s known as an “as if complete” valuation: an estimate of what the finished home should be worth, based on the specifications in your contract, as though it existed today.
That gap between “valued as if complete today” and “actually completed in a future market” is where a lot of the settlement risk in off-the-plan buying comes from. The valuation isn’t a prediction of where the market will be in one to three years — it’s a snapshot, applied to something that won’t exist for a while yet.
Why Off-the-Plan Comparable Sales Are Harder to Pin Down
Every valuation leans on comparable sales — genuine, recent, arm’s-length transactions of similar properties nearby. For an established three-bedroom house in a suburb with plenty of turnover, that’s usually straightforward. For a brand-new apartment in a brand-new building, it often isn’t.
Valuers are generally expected to rely on sales that are recent, commonly within about six months, and many are cautious about leaning too heavily on other off-the-plan sales within the very same development, on the basis that a string of related developer sales might not represent a genuinely independent market. Where there’s limited sales history nearby — a new precinct, a first-of-its-kind building, or simply low sales volumes — this caution can work against the buyer, producing a valuation that’s more conservative than the eventual resale market might support.
Some lenders have also tightened how they handle the final check, sending a valuer through the near-finished building in person before releasing loan funds, rather than relying only on plans and a desktop assessment. That’s sensible risk management for the lender, but it also means the number you’re contractually committed to can still be tested right up to the pointy end of the process.
The Valuation Shortfall Problem — And What Happens If the Numbers Don’t Match
Here’s the scenario every off-the-plan buyer should understand before signing. Say you exchange contracts on an apartment for $650,000, with a 10% deposit. Eighteen months later, construction finishes, and your lender’s valuer comes back with a completed valuation of $600,000. Your lender will generally only lend against the lower of the two figures — the valuation, not the contract price. If you were relying on an 80% loan, you’d now be borrowing 80% of $600,000, not $650,000, and the $50,000 difference has to come from somewhere else, on top of the deposit you’ve already paid.
This isn’t a rare, worst-case scenario dreamed up to scare buyers. It’s a well-documented pattern that’s shown up repeatedly in Australian property media and industry commentary, particularly in inner-city apartment markets during periods of heavy new supply. It tends to bite hardest for buyers who exchanged during a rising market, borrowed close to their maximum capacity, or bought into a large tower with limited genuine resale history to draw on.
There’s a related risk worth flagging too: Building industry insolvency risk should also be considered carefully, with buyers able to review broader trends through ASIC insolvency statistics, with well over 2,000 building companies entering external administration in some recent financial years, according to ASIC data. Off-the-plan deposits are generally required to be held in a trust account rather than paid straight to the developer, which offers some protection — but if a builder or developer collapses mid-project, getting that money back and working out what happens to your contract can still take time and legal costs.
If Your Settlement Valuation Comes in Low
If your completed valuation lands below your contract price, you generally have a handful of realistic options, and it’s worth talking them through with your mortgage broker and conveyancer or solicitor before assuming the worst:
- Get a second valuation or try a different lender. Valuations can vary between valuers and between lenders’ panels, so a second opinion sometimes closes some or all of the gap.
- Ask what the valuation did and didn’t account for. If your contract includes upgrades or inclusions the valuer may not have fully factored in, raise it with your broker.
- Fund the shortfall yourself. Savings, a family guarantee, or a slightly higher loan-to-value ratio (usually with lenders mortgage insurance attached) can bridge the gap, though this adds cost.
- Talk to the developer. They don’t have to renegotiate, but in a softer market some will discount, extend settlement, or offer incentives rather than risk a failed settlement.
- Understand your contractual exit rights. Most off-the-plan contracts don’t let you walk away simply because your valuation came in low — that risk generally sits with the buyer. If settlement genuinely isn’t achievable, get legal advice quickly about your position on the deposit, rather than letting the date pass.
Getting a Pre Purchase Valuation Before You Exchange
A pre purchase valuation for an off-the-plan property is usually a desktop-style assessment, since there’s often nothing to physically walk through yet. A Certified Practising Valuer, accredited through the Australian Property Institute, will typically review your contract, plans and finishes schedule, then weigh that against genuine comparable sales — similar completed apartments or townhouses nearby, and where appropriate, sales in other comparable developments in the area.
Cost varies by valuer, location and property type, but a standard residential valuation report in Australia generally runs somewhere between roughly $300 and $600 or more. That’s a modest outlay against a purchase price running into the hundreds of thousands, particularly if it stops you signing up to a price that’s meaningfully above where the market actually sits.
Timing matters. Ideally, you’d get this done before you exchange contracts, or during any cooling-off period or finance condition your contract allows — once you’ve exchanged unconditionally, your ability to act on an unfavourable valuation is far more limited. It’s worth being upfront with the valuer that the report is for your own decision-making rather than a lender, so they understand the purpose and can flag anything unusual about the pricing or the comparable sales being used.
It’s also worth knowing this isn’t just buyer caution talking. The Australian Property Institute has recently pushed for independent pre-sale valuations to become standard practice more broadly across residential transactions in New South Wales and Victoria, arguing that a real estate agent setting a price guide has an inherent conflict of interest that only an independent valuer can properly counter. Off-the-plan buyers face an even sharper version of that problem, since the price is set entirely by the developer rather than tested through an open market campaign.
Contract Protections Every Off-the-Plan Buyer Should Check
Beyond the valuation question, a handful of contract terms have a direct bearing on your financial exposure, and they’re worth reading — or having your solicitor or conveyancer explain — before you sign anything.
Sunset Clauses
Almost every off-the-plan contract contains a sunset clause: a date by which the plan of subdivision must be registered, or the building completed, failing which either party can walk away. These clauses exist for legitimate reasons, but they were also, at times, used by some developers to cancel contracts once the sunset date passed and resell the same properties at higher prices in a rising market.
Both New South Wales and Victoria have since tightened the rules. Under changes introduced in NSW in 2015 and Victoria in 2019, a developer generally can’t rely on a sunset clause to rescind a contract unless the buyer consents in writing, or the developer obtains an order from the Supreme Court permitting it. That’s a meaningful protection, but it’s still worth knowing what your sunset date actually is and what your rights are as it approaches.
Deposit Protection and Developer Risk
Off-the-plan deposits are generally required to be held in a trust account rather than handed straight to the developer, which offers a layer of protection if the project runs into trouble before completion. That said, if a developer or builder does become insolvent, recovering trust funds and working out the status of your contract can still take considerable time and legal costs — trust account protection reduces risk, but it doesn’t eliminate the inconvenience.
It’s worth doing some homework on the developer itself: their track record on previous projects, whether those were finished on time and to the standard promised, and their general financial standing. A pattern of delays or disputes on past projects is a reasonable signal to weigh alongside the valuation question.
Stamp Duty, Grants and the 2026 Tax Changes Off-the-Plan Buyers Should Know About
Off-the-plan property doesn’t just carry valuation risk — it also comes with tax and duty settings that vary by state and have shifted meaningfully in 2026. It’s worth checking these against your own situation with your accountant or conveyancer, since a favourable tax setting doesn’t fix an unfavourable price.
State-by-State Differences
- Victoria has run a temporary off-the-plan land transfer (stamp) duty concession, available to all buyers including investors, that can cut duty substantially compared to the standard rate. These temporary concessions have been extended more than once, so confirm the current cut-off date with the State Revenue Office or your conveyancer rather than relying on a date you’ve read elsewhere.
- New South Wales doesn’t run a specific off-the-plan discount on the duty rate itself, but owner-occupiers buying off the plan can generally defer paying transfer duty for up to 12 months (or until settlement, if earlier), provided they meet residency requirements. This deferral generally isn’t available to investors or to foreign persons.
- Queensland significantly expanded its First Home Concession from May 2025, giving eligible first home buyers a full transfer duty exemption on new homes, including off-the-plan purchases, with no price cap, alongside a home concession that scales down as property values rise.
- Western Australia has also extended its own off-the-plan duty concession in recent state budgets.
Because these settings change with almost every state budget, treat any specific figure or cut-off date you read, including in this article, as a starting point for a conversation with your solicitor or conveyancer, not the final word.
Why New Builds Are Attracting Extra Attention in 2026
The 2026-27 Federal Budget, handed down in May 2026, made the most significant change to negative gearing and capital gains tax treatment for residential property in decades. From 1 July 2027, negative gearing will no longer be available for established residential investment properties bought after 7:30pm on budget night — losses on those properties can only be offset against rental income or future capital gains, not salary. The 50% CGT discount on established property is also being replaced with cost base indexation and a minimum tax rate on net capital gains.
Eligible new builds, including many off-the-plan purchases, are carved out of both changes. They can retain full negative gearing against other income and the existing 50% CGT discount. That’s a genuine, current reason investors are looking more closely at off-the-plan and new-build property in 2026 than they might have a year or two ago.
None of that changes the core question this article is about, though. A favourable tax setting on a new build doesn’t make an inflated contract price reasonable, and it’s a separate issue from whether the bank’s completed valuation will match what you’ve agreed to pay. If the way you use the property changes down the track — say you live in it for a while before eventually renting it out — that kind of change can sometimes trigger a need for an independent market valuation at that point for tax purposes, so it’s worth asking your accountant whether this applies to you and keeping your original pre purchase valuation on file as one piece of that record.
It’s also worth knowing that off-the-plan and other new dwellings are, in practice, the main way non-resident foreign buyers can purchase residential property in Australia, since foreign non-residents generally can’t buy established homes at all. If you’re buying as a foreign person or temporary resident, budget for Foreign Investment Review Board (FIRB) application fees and a state-based foreign purchaser duty surcharge, commonly in the order of 7% to 8% on top of standard stamp duty, since these materially change the total cost.
So, Do You Need a Pre Purchase Valuation for Your Off-the-Plan Purchase?
There’s no rule saying every off-the-plan buyer must get an independent pre purchase valuation before signing. But the case for one gets stronger the more of these apply to you:
- You’re borrowing close to your maximum capacity, so even a modest shortfall would be hard to fund.
- You have limited cash buffer beyond your deposit and other settlement costs.
- You’re buying into a large development, a first-of-its-kind project, or an area with limited recent sales history.
- Settlement is a year or more away, giving the market more time to move in either direction.
- You haven’t dealt with this developer before, or you’re relying on marketing materials and a display suite rather than independent research.
If most of those don’t apply, the case is a little less urgent, though a valuation still doesn’t hurt. For most off-the-plan buyers, though, a pre purchase valuation is one of the only genuinely independent checks available on a price that’s set entirely by the seller, before an open market ever gets the chance to test it. Similar buyer strategies for assessing property value can also help purchasers make more informed decisions when competition influences pricing.
FAQs
Is a pre purchase valuation the same as the valuation my bank does?
No. A pre purchase valuation is one you commission independently, usually before you exchange contracts, purely to check whether the price is fair. Your bank’s mortgage valuation happens separately, generally closer to settlement, and exists to protect the lender’s security rather than to advise you.
Can a valuer actually value a property that hasn’t been built yet?
Yes, though it’s a different exercise to valuing a finished home. Valuers typically produce an “as if complete” valuation, based on your contract’s plans and finishes schedule, weighed against comparable sales of similar completed properties nearby.
What happens if my off-the-plan valuation comes in lower than my contract price?
Your lender will generally only lend against the lower figure, meaning you’ll need to fund the gap yourself, take on a higher loan-to-value ratio (often with lenders mortgage insurance), or negotiate with the developer. It’s rarely grounds to walk away from the contract without penalty, so check your options early.
How much does an independent pre purchase valuation cost?
A standard residential valuation report in Australia typically costs somewhere between roughly $300 and $600 or more, depending on the valuer, property type and location.
Do I still need a valuation if I’m buying with cash?
It’s less financially urgent since there’s no lender to satisfy, but a pre purchase valuation still tells you whether you’re paying a fair price rather than a developer’s asking price.
What’s a sunset clause, and could I lose my off-the-plan property because of one?
A sunset clause sets a date by which the development must be registered or completed, after which either party can rescind. In NSW and Victoria, a developer generally needs your written consent or a Supreme Court order to rescind under a sunset clause, which limits, but doesn’t entirely remove, the risk.
Can foreign buyers purchase off-the-plan property in Australia?
Generally, yes. Off-the-plan and other new dwellings are one of the main categories of residential property non-resident foreign buyers can purchase, subject to FIRB approval, application fees, and a state-based foreign purchaser duty surcharge on top of standard stamp duty.
Conclusion
Buying off the plan means agreeing today on a price for a home that won’t exist for a year or more, and the bank’s eventual valuation won’t always match it. An independent pre purchase valuation, read alongside your contract’s sunset clause and current stamp duty settings, is one of the simplest checks available before you’re locked in — a modest cost against a genuinely significant commitment.
If you’d like an independent opinion before you exchange on an off-the-plan property, Capital Gains Tax Valuations can prepare a pre purchase valuation report based on your contract, plans and finishes schedule. Call the team on +61 438 080 786 to talk through what’s involved for your specific purchase.